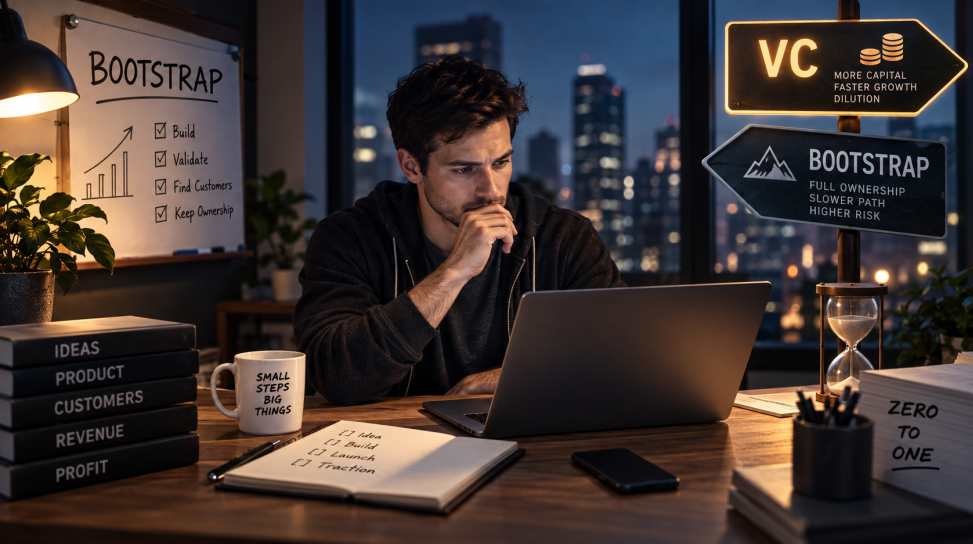
The Bootstrapper’s Dilemma: Funding the Zero-to-One Phase Without Early Dilution
 Daniel Levi
Posted On September 21, 2026

In a volatile venture market where seed-stage checks demand proven retention numbers and enterprise pilots, raising external funds before you have a product is remarkably difficult. Venture funds and angel syndicates that previously wrote checks on pitch decks now expect built software and customer feedback before scheduling partner meetings.
This environment has forced founders to rethink the standard playbook. Rushing to accept dilutive term sheets before validating a core hypothesis often means selling twenty or twenty-five percent of a company at a depressed valuation, setting an aggressive governance structure in place before the software even finds a repeatable use case.
To bridge the gap between initial code commits and genuine institutional leverage, more technical operators are looking away from venture capital and toward nontraditional liquidity sitting directly on their personal balance sheets.
The Hidden Cost of Raising Capital Too Early
Taking external checks before achieving basic distribution metrics carries long-term consequences that go well beyond the initial cap table math:
- Aggressive valuation caps: Giving away substantial equity at pre-seed pricing anchors your corporate ownership low, severely restricting your ability to assemble an attractive stock option pool for critical early hires.
- Loss of tactical agility: Bringing institutional representation into the boardroom before establishing clear product-market fit forces founders into rapid scaling motions when they should still be experimenting freely.
- Misaligned growth cadences: Venture incentives favor exponential burn to chase category dominance, which directly conflicts with building an efficient, cash-flow-positive utility.
Maintaining ownership through the fragile discovery window lets founders protect their vision until unit economics genuinely justify rapid institutional fuel.
Why Founders Run Out of Personal Runway
Bootstrapping a software company has never been computationally cheaper, but human capital remains expensive.
Even with modern cloud infrastructure and developer automation lowering server expenses, hiring exceptional machine learning talent, covering contract compliance reviews, and sustaining baseline living expenses while drawing zero salary quickly drains personal reserves.
Founders frequently enter development cycles relying on personal savings accounts and liquid equities. However, burning through high-yield cash cushions leaves zero margin for family emergencies, while selling diversified investment portfolios often triggers significant capital gains taxes that eat into development budgets.
Relying on unsecured credit cards or high-interest personal lines is equally destabilizing. Floating payroll or consulting invoices on revolving credit lines introduces variable borrowing rates that distract operators from product execution, creating monthly cash flow panic at the worst possible moment.
Tapping Dormant Balance Sheet Leverage
To sidestep predatory equity haircuts and high-interest consumer debt, founders with real estate are increasingly exploring collateralized non-venture financing.
Instead of giving away an outsized chunk of equity before writing a line of viable code, many founders simply leverage their illiquid net worth and apply for a home equity loan to self-fund the early architecture on their own timeline.
Having structured liquidity on standby changes how a small engineering team operates. It secures twelve to eighteen months of dedicated development runway, covers initial infrastructure tiers, and buys the breathing room required to ship a production-grade beta without living in constant terror of an empty corporate bank account.
Treating Injected Founder Capital as Professional Debt
Using private asset leverage to support an early-stage company requires strict operational discipline. Blurring the line between personal finances and venture development is how inexperienced founders get into trouble:
- Formalize shareholder loan terms: Document personal cash injections into the business as structured debt notes with clear repayment timelines and realistic market-rate interest return triggers once the company hits enterprise milestones.
- Isolate development milestones: Allocate borrowed funds toward clear value-accretive levers like core engineering sprint milestones or enterprise compliance certifications rather than discretionary digital marketing.
- Set hard liquidity guardrails: Never commit the full collateralized loan value into initial operations; keep a defensive portion reserved in cash to service debt independently of corporate revenue ramps.
Treat personal financial injections as disciplined business debt so founder capital works like an institutional tool rather than an emotional subsidy.
Reaching Institutional Tables From a Position of Strength
Venture capital remains an incredible tool for hyper-scaling a business once distribution channels are clear. The critical error is relying on venture funds to discover that formula in the dark.
When you fund your initial development independently, the dynamic shifts entirely when you eventually decide to sit down with growth funds. Instead of appearing as a desperate founder looking for money to survive the quarter, you present an operational software engine backed by real users, proprietary code, and an unburdened cap table.
Protecting your equity through the early slog gives you real corporate leverage. By deploying predictable, non-dilutive personal borrowing structures during the earliest development phases, you retain control of your business until you are ready to scale on your own terms.
The Bootstrapper’s Dilemma: Funding the Zero-to-One Phase Without Early Dilution