Meta classified Zuckerberg as a researcher to claim $355 million tax break on $4.1 billion pay, NYT reports
 Daniel Levi
Posted On September 30, 2026
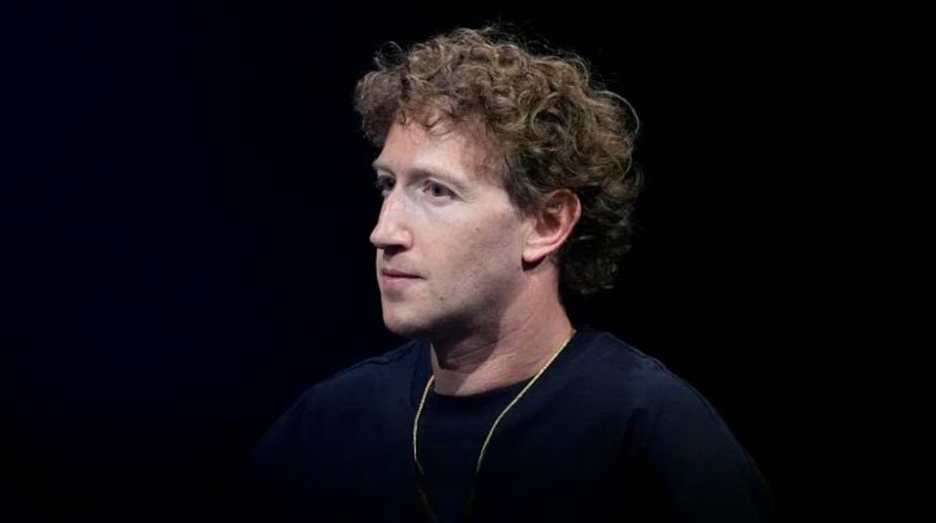
Meta turned billions of dollars in Mark Zuckerberg’s stock compensation into a research tax break, arguing that its CEO’s work building Facebook qualified him for a federal government incentive for technological research.
The company claimed roughly $355 million in tax savings tied to $4.1 billion in stock options Zuckerberg exercised, according to a New York Times report citing court filings. The Internal Revenue Service wants that money back.
“In 2013, Meta claimed that $4.1 billion of stock options exercised by Mr. Zuckerberg counted as a research expense because he helped invent new software, such as Facebook’s News Feed. The I.R.S. is trying to claw back the company’s resulting $355 million in tax savings,” the New York Times reported, citing court filings.
The dispute dates to Facebook’s 2012 and 2013 tax years and centers on whether Zuckerberg’s stock compensation qualified as wages paid for research under Section 41 of the U.S. tax code. Meta claimed $618 million in research credits across those two years, with about $355 million connected to Zuckerberg’s options, according to Bloomberg Tax.
Meta’s argument rests on Zuckerberg’s direct involvement in creating Facebook’s technology. In court filings, the company said Zuckerberg personally wrote software and oversaw development of Facebook’s technology when the stock options were granted in 2005. Meta cited his role in products such as Facebook’s News Feed as evidence that his work qualified as research.
That leaves the IRS and Meta fighting over an unusual question: Can billions of dollars in a founder’s stock compensation become a research expense if that founder helped create the technology behind the company?
Meta and the IRS disagree over when Zuckerberg’s work counts
The dispute gets more complicated when the timing of Zuckerberg’s options comes into play.
Meta argues the court should focus on 2005, when the options were granted, and Zuckerberg was deeply involved in developing Facebook’s software. The IRS says the relevant period ran from January 2008 through November 2010, when the options vested.
The agency has raised another objection. According to Bloomberg Tax, the IRS pointed to language in Zuckerberg’s stock-option agreement stating that the options were not granted for services performed before the vesting commencement date. Meta says its treatment followed longstanding IRS guidance governing stock-based compensation and research credits.
There is precedent for stock options entering research-credit calculations. In earlier cases involving Apple and Sun Microsystems, courts concluded that gains from certain employee stock options could count as wages for purposes of calculating qualified research expenses. IRS guidance later acknowledged those decisions.
Meta’s fight over Zuckerberg’s compensation is part of a much larger tax battle surrounding the company.
The Times reported that Meta has recently used the federal research credit for AI infrastructure, treating certain AI data centers and Nvidia chips as experimental research investments. The strategy helped push Meta’s research-related tax savings from roughly $700 million in 2023 to $3.9 billion in 2025, according to the report.
Meta has taken a similar approach with its AI infrastructure. The company classified some of its AI data centers as “experimental pilot facilities” on its tax returns, according to The New York Times, allowing the Nvidia chips inside them to qualify for the federal research tax credit.
The tax benefit has grown dramatically. Meta’s research-credit savings rose from about $700 million in 2023 to $3.9 billion in 2025, the Times reported, as its federal tax bill fell nearly 71%. Meta’s $3.9 billion claim alone represented more than 10% of the entire federal research credit claimed that year.
The facilities involved are enormous. One Meta AI campus in Louisiana is planned at 5 gigawatts and is expected to cost more than $50 billion.
The scale of Meta’s tax position is matched by the amount it has set aside for possible challenges. The company’s reserve for uncertain tax positions grew 45% to $18.74 billion, reflecting the potential exposure if the IRS rejects some of its claims
Meta’s own filings show how large the exposure has become. As of June 30, 2026, the company reported $18.74 billion in gross unrecognized tax benefits, primarily tied to uncertainty surrounding research tax credits and transfer pricing with foreign subsidiaries.
Meta maintains that its tax positions are legitimate. The company is now asking the Tax Court to agree that Zuckerberg’s early work writing code and directing Facebook’s technology can turn part of one of Silicon Valley’s biggest stock paydays into qualified research spending.
The IRS sees it differently, and $355 million now hangs on which interpretation survives in court.