Venture Capital & Startup Funding Roundup, August 10, 2026: Accel, Coatue Management, General Atlantic, Khosla Ventures, Sequoia Capital, & More
 Nickie Louise
Posted On August 10, 2026

The biggest funding news today underscores how investors are doubling down on critical infrastructure – from national security and AI data centers to energy storage and fintech – even as deal activity remains focused on proven themes. A UK drone-defense startup raised a blockbuster round as governments scramble to counter cheap attack drones; a San Jose optical‐connectivity startup emerged from stealth with a $5.5B valuation to solve AI “wiring” bottlenecks; and an American clean-energy firm raised over $1B to put batteries in homes amid surging grid demand. Meanwhile, fintech and proptech startups are also in focus: a Silicon Valley–backed startup bank reportedly in talks for a $1.5B raise and a UK rentals marketplace closed a hefty $170M Series B. In short, capital is flowing into startups tied to AI infrastructure, resilience and defense, and the new economy’s plumbing.
Indeed, there is a marked theme: infrastructure acceleration. In the past 24 hours alone, investors have poured money into companies building the underpinnings of the next tech era. Lumilens’ $700M Series C highlights the AI compute arms race – optical interconnects to link thousands of GPUs as data centers strain under an expected $2.8 trillion AI hardware market by 2029. Base Power’s $1B round reflects a climate-conscious bet on home battery systems, as U.S. electricity demand hit record levels in 2025. And Cambridge Aerospace’s $300M raise signals a defense-tech surge: its low-cost anti-drone interceptors combat a new asymmetric threat, where each $20k attack drone can trigger a $1M missile shot. These rounds – along with others today – show investors shoring up technology and energy infrastructure for a future shaped by AI, geopolitical tensions, and climate challenges. We’ll break down the top rounds below and what they signal for founders and investors.
The Macro Environment: Infrastructure and Resilience Race
Venture capital is again clustering around tangible infrastructure and defense as much as pure software innovation. After years of chasing metaverse apps and mobile marketplaces, today’s largest rounds are hardware- and systems-oriented. Government budgets and industrial demand are pulling money into startups that help address new bottlenecks. For example, AI and data-center expansion have driven U.S. power usage to new heights. Both cloud hyperscalers and AI startups are hungry for energy storage and distribution solutions – hence Base Power’s $1B Series D (at a $13B valuation) to build U.S.-made home battery systems for grid stabilization. Similarly, Lumilens raised $700M at a $5.51B valuation for optical chips that replace copper wiring between GPUs, tackling an acute shortage of high-speed transceivers. (Citigroup estimates AI infrastructure spending will reach $2.8T by 2029, making network “wiring” as critical as compute.)
Defense and security form another powerful sub-theme. The Ukraine war and regional drone strikes have lit a fire under both investors and governments. Cambridge Aerospace (UK) pulled in $300M to scale its anti-drone missile tech – reflecting an environment where fleets of $20K kamikaze drones are forcing defenders to fire $1M interceptors. In parallel, cyber defense is getting the AI treatment: Tel Aviv–based Corma emerged from stealth with $60M to build “defensive cybersecurity” AI models, led by top-tier VCs (Sequoia, Khosla, Coatue). These investments suggest a bifurcation: startups that enable offensive AI (attack automation) are already well funded, but now defenders are racing to catch up.
Financial infrastructure for startups is also under the spotlight. Silicon Valley’s reliance on a few tech-friendly banks was brutally exposed by SVB’s collapse, and some VCs are seeding new players. Palmer Luckey’s Erebor, a digital-first bank targeting AI, crypto and defense companies, is reportedly in talks for a massive $1.5B raise at an $8B pre-money valuation. Although still unofficial, that deal – if it closes – highlights investors’ hunger to build a new tech banking hub from the ruins of SVB.
Finally, the deals signal a new imbalance between private and public markets. Stock-market lockups (like Nvidia’s) and macro uncertainty have kept IPOs at bay, pushing late-stage rounds to astronomical levels. Whatnot, a live-commerce marketplace, just secured $545M at a $20B price – nearly doubling its value in nine months. Similarly, Lumilens’ stealth debut comes loaded with capital ($700M) despite no revenue publicly disclosed. In this environment, savvy investors are treating valuations more like testaments to future system-level demand (AI networks, grid storage, defense readiness) than to traditional revenue multiples. For founders, that means enormous war chests are available for infrastructure plays – but only if the technology truly addresses these macro challenges.
Cambridge Aerospace raises $300M in funding to intercept cheap drones

A Cambridge, England startup has secured one of today’s biggest rounds: $300 million in a Series C at a $3.4 billion valuation. Cambridge Aerospace builds low-cost interceptor missiles (the “Skyhammer” system) to shoot down Iran-style attack drones. Its CEO, ex-MIT engineer Steven Barrett, notes a single $20K kamikaze drone can force the use of a $1M Patriot missile. Those math and defense-budget pressures caught investors’ attention, leading DFJ Growth to lead this round. Returning backers Lux, Accel and Lakestar (and early investor Never Lift) also participated.
This round more than doubled Cambridge Aerospace’s valuation in four months (after a $200M Series B at $1.3B in April), underscoring a “defense tech arms race” in Europe. The company is already under contract with the UK Ministry of Defense to deploy Skyhammer interceptors against drones. With this capital, Cambridge Aerospace plans to scale manufacturing in the UK and allied countries. Competitors like Stark and Helsing have raised similar sums for offensive drone and weapon systems; Cambridge Aerospace focuses on the defense side. Analysts note the anti-drone market may reach tens of billions in the coming decade.
Investors are betting that the ability to cheaply shoot down drones is as critical as building them. In an age of swarm attacks and autonomous UAVs, governments cannot rely solely on expensive legacy missiles. If Cambridge’s interceptors work, it could reshape NATO’s budgets and procurement. (The UK’s defense “unicorn” scheme and recent £2.1B in state investment into startups suggest strong backing for such solutions.) For founders in defense, the takeaway is clear: backers will fund founders who can dramatically lower the cost-per-threat against new adversaries.
Funding Details
Startup: Cambridge Aerospace
Investors: DFJ Growth (lead), Lux Capital, Accel, Lakestar, Never Lift, Ora Global, others
Amount Raised: $300 million
Total Raised: ~$636 million (all rounds)
Stage: Series C
Date: Aug 10, 2026
HQ: Cambridge, UK
Sector: Defense (anti-drone) tech
Corma raises $60M in funding to build AI defenders for cyber

Tel Aviv and San Francisco-based startup Corma emerged from stealth with a $60M seed round led by Sequoia Capital (joined by Khosla Ventures and Coatue). The young company is training AI models specifically for cyber defense, as opposed to offense. Its founder, ex-DeepMind engineer Alon Pluda, points out that today’s large language models are already excellent at finding software bugs and writing exploit code – skills that attackers can weaponize. In head-to-head simulations, AI red teams succeeded 88% of the time against old-school tools.
By contrast, Corma’s models are being built “from the ground up” to sift through logs, alerts, and network traffic at machine speed. Early deployments in Fortune 100 firms – across healthcare, finance, energy and infrastructure – reportedly cut threat-response times by over 90%. Sequoia’s Shaun Maguire says Corma is “building the intelligence layer defense actually needs”. Investors clearly see the gap: putting $60M into a weeks-old startup signals urgency.
This round matters because it illustrates an inflection: AI-driven cyberattacks are far outpacing defenders today, so the next battleground will be AI vs. AI. For enterprises, Corma positions itself as a digital security team member rather than a dashboard. If it succeeds, it could set the template for future security stacks – akin to how startups like BigID reshaped data privacy. The high valuation and pedigree (centers of excellence in AI and Israel’s Unit 8200) also send a message: cybersecurity funds are still flowing to world-class teams, despite a softening VC market.
Funding Details
Startup: Corma
Investors: Sequoia Capital (lead), Khosla Ventures, Coatue Management
Amount Raised: $60 million
Total Raised: $60 million (first disclosed round)
Stage: Seed
Date: Aug 10, 2026
HQ: Tel Aviv & San Francisco, USA/Israel
Sector: Cybersecurity (AI-driven defense)
Whatnot raises $545M in funding at $20B for live commerce
Whatnot, a live-streaming marketplace for collectibles and fashion, closed a huge $545M Series G at a $20B valuation. Led by ICONIQ, Lightspeed and Avra, the round brought in new backers like Kleiner Perkins, Wellington, and Robinhood Ventures, and included all of Whatnot’s prior investors (CapitalG, Y Combinator, a16z, DST, etc.). Remarkably, Whatnot nearly doubled in value since last fall’s $11.5B round – a sign that investor appetite for consumer commerce is still strong.
Whatnot has exploded in usage: it saw over $8B in GMV in H1 2026, surpassing its full 2025 sales. On Whatnot’s streams – selling everything from Pokémon cards to streetwear – small sellers can reach millions of viewers (beating platforms like eBay’s live auctions or TikTok Shop on native commerce). Icons like Gucci have recently launched live events on the platform. With this capital, Whatnot plans international expansion (Europe is growing 360% YoY) and new AI tools for sellers.
For investors, Whatnot’s success signals that “livestream commerce” may finally be mainstream. It also suggests a broader point: platforms that once seemed niche (like live auctions for collectibles) can scale rapidly with the right network effects and tech. Founders should note: even in an AI-dominated narrative, vertical marketplaces that solve real buyer-seller matching (with a social twist) can still raise massive rounds. That said, the high $20B price tags require clear evidence of continued user growth and monetization.
Funding Details
Startup: Whatnot
Investors: ICONIQ Capital, Lightspeed Venture Partners, Avra Ventures (lead); others: Kleiner Perkins, Wellington, Robinhood Ventures, S32, Standard Capital; plus existing backers
Amount Raised: $545 million
Total Raised: ~$1.5 billion (since 2019)
Stage: Series G
Date: Announced Aug 9, 2026 (Tech Funding News)
HQ: Palo Alto, USA
Sector: E-commerce / Live Commerce Marketplace
Base Power raises $1B in funding for home battery storage
Base Power, an Austin-based energy storage startup, announced a $1B Series D at a $13B valuation. The round was led by Ribbit Capital, Addition, Valor Equity and JPMorgan Chase’s venture unit, marking it as one of the year’s largest cleantech deals. Base Power makes backup batteries for homes (think Tesla Powerwall) and said it’s already started U.S. manufacturing of its new system.
The timing reflects grid pressures: record U.S. power use in 2025 and exploding AI/data-center demand have utilities scrambling for storage solutions. Base Power has deployed over 500 MWh of batteries to date, but will use this cash to ramp manufacturing and partnerships (already announced deals with Austin Energy, El Paso Electric, etc.). CEO Dave Hardin told Reuters the funds will help bring their batteries to more customers amid “surging power demand.”
Strategically, this round shows venture money flowing into the “electrification” theme again. Home batteries are now seen as essential grid infrastructure – earning as much capital as electric cars. For founders: if your startup bridges a gap in the grid (resilience, renewable integration, AI-powered demand smoothing), well-capitalized investors are available. The investor group – including Ribbit and banks – underscores confidence that home energy systems will see mass adoption.
Funding Details
Startup: Base Power
Investors: Ribbit Capital, Addition, Valor Equity Partners, JPMorgan Chase Strategic Investment Group (lead)
Amount Raised: $1 billion
Total Raised: $2.5 billion (to date)
Stage: Series D
Date: Aug 3, 2026
HQ: Austin, USA
Sector: Energy Infrastructure (Home Battery Storage)
Sierra Space raises $550M in funding as space-defense bets surge
Sierra Space, the aerospace firm behind the reusable Dream Chaser spaceplane, closed a $550M Series C (raised in March) at an $8B valuation. The round was led by LuminArx and included General Atlantic, Coatue and other existing investors. The Colorado company will use the funds to expand manufacturing of satellites and develop defense and intelligence solutions – government contracts being a key focus.
Sierra Space’s big round reflects the broader trend of defense-oriented space ventures commanding high valuations. Many VCs are “doubling down on space tech” amid geopolitical tension, especially companies with existing production lines and government deals. Sierra Space already has a $450M Pentagon award (satellites) and NASA contracts for cargo flights, so investors view this as de-risked aerospace. The CEO noted that scaling manufacturing for defense missions is now the priority.
For founders in space or defense, Sierra’s case is instructive: Projects once deemed risky (spaceplanes, satellites) can attract huge capital if they align with national security needs. Valuations in this sector are now comparable to climate tech (both see government backing). On the flip side, commercial-only space plays (e.g., passenger space tourism) are less likely to get this level of funding today.
Funding Details
Startup: Sierra Space
Investors: LuminArx (lead), General Atlantic, Coatue, Moore Strategic Ventures, Andalusian Private Capital
Amount Raised: $550 million (Series C)
Total Raised: $1.1+ billion (incl. Series B)
Stage: Series C
Date: Mar 5, 2026
HQ: Louisville, Colorado, USA
Sector: Space Tech / Defense (satellites & spacecraft)
Commonwealth Fusion Systems raises another $1B in equity
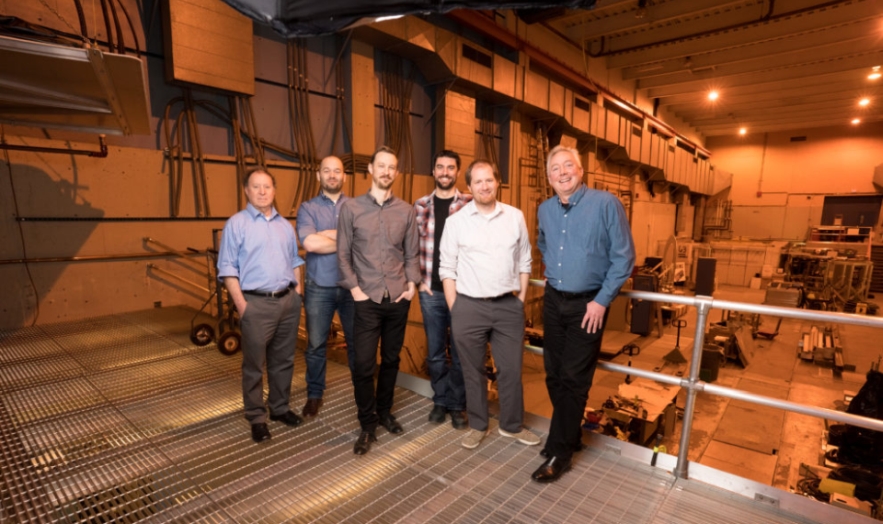
Energy startup Commonwealth Fusion Systems (CFS) closed a huge equity round last week: $1 billion of new capital, bringing its total funding to $4 billion. (Notably, CFS raised $863M in late 2025 as well.) This latest raise drew in a new slate of institutional investors (pension funds, sovereign wealth funds, industrial partners), indicating growing mainstream confidence. CFS is racing to complete its SPARC prototype and eventually the ARC power plant.
This is arguably the largest funding round yet for a private fusion startup. It dwarfs the $188M biotech deals and shows how “energy innovation” is capturing big dollars. CFS will use the capital to “accelerate progress to commercialization”, essentially funding the final steps toward a working fusion demo. For context, CFS says its $4B total is about 30% of all fusion funding ever – a testament to investor bullishness.
Implications: Fusion is moving from lab curiosity to borderline government project, at least funding-wise. Backers (including BlackRock/Temasek, Bezos, Mitsubishi) are placing large bets on carbon-free baseload energy. For founders, fusion’s influx of billions (and high valuations) raises questions about funding distribution: while public markets have devalued many tech sectors, “hard science” breakthrough companies with plausible roadmaps can still tap deep pockets. However, these companies must justify their cap tables with near-term milestones (e.g., CFS points to SPARC construction).
Funding Details
Startup: Commonwealth Fusion Systems (CFS)
Investors: New institutional lead partners (incl. pension, SWF, infrastructure funds), plus existing backers (private investors)
Amount Raised: $1 billion (additional equity)
Total Raised: $4 billion (to date)
Stage: Late-stage private equity
Date: Announced Aug 3, 2026 (World Nuclear News)
HQ: Devens, Massachusetts, USA
Sector: Clean Energy (Nuclear Fusion)
Erebor bank in talks to raise $1.5B in funding at $8B valuation
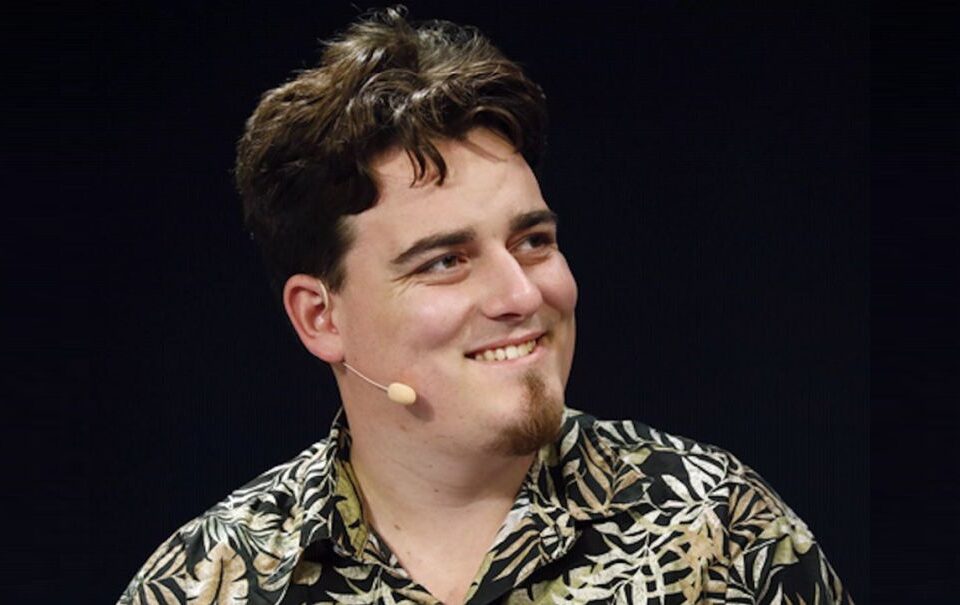
Not a startup in the traditional sense, but worth noting: Erebor, a Columbus, Ohio–based tech-focused bank backed by Palmer Luckey (creator of Oculus and co-founder of Anduril), is reportedly in advanced talks to raise roughly $1.5 billion at an $8 billion pre-money valuation. If completed, this would be one of the largest non-SPAC fintech raises ever (though it’s still unofficial, pending deal closure).
Erebor launched in 2025 to serve companies that struggle with traditional banks – especially in AI, defense, crypto and manufacturing. Its deposit base has quadrupled since spring, reaching ~$4B by summer. Major Silicon Valley VCs (Lux Capital, a16z, Valor Equity) and Palantir’s Joe Lonsdale are lining up for the round. The pitch: companies driving the next tech wave need a new kind of banking infrastructure.
This news speaks to a wider trend: investors are underwriting the rebuild of fintech plumbing. The SVB collapse left many startups scrambling; Erebor’s rapid rise suggests venture sees a big opportunity in banking for tech-sector clients. For founders, it’s a reminder to watch not just product-market fits but also the financial ecosystem that supports startups. Banks that understand startup cash cycles and risks can command high premiums – and deep-pocketed VCs are ready to back the winners.
Funding Details
Startup: Erebor (Tech Banking)
Investors: Lux Capital, Human Capital, Valor Equity Partners, Andreessen Horowitz, SV Angel (rumored participants)
Amount Raised: ~$1.5 billion (expected)
Total Raised: Undisclosed (early-stage)
Stage: Growth (bank equity round)
Date: Reported Aug 10, 2026
HQ: Columbus, Ohio, USA
Sector: Financial Services (Fintech Infrastructure)
Dwelly raises $170M in Series B funding to build an AI-powered lettings platform
London-based proptech startup Dwelly has raised $170 million in Series B funding, giving the company substantial firepower for an ambitious consolidation strategy in the UK rental market. Rather than building another property-search portal, Dwelly is acquiring independent letting agencies and bringing their operations onto a technology platform that uses AI and automation to handle much of the administrative work behind property management.
The opportunity is rooted in fragmentation. The UK lettings industry includes thousands of independent agencies, many still operating with labor-intensive processes across tenant communications, property management, compliance, maintenance, and back-office administration. Dwelly’s thesis is that acquiring these businesses and centralizing much of that work can create a more efficient national platform while preserving the local relationships that make smaller agencies valuable.
The size of the Series B is particularly notable for a proptech company. Dwelly co-founder and chief product officer Dan Lifshits said another financing could come relatively soon, suggesting the company sees a considerably larger acquisition opportunity ahead. The strategy effectively combines software economics with a roll-up model: instead of waiting for agencies to adopt its technology, Dwelly can acquire the businesses themselves and deploy its operating system across them.
That makes execution the bigger question. Roll-ups can generate scale quickly, but integrating acquired companies, maintaining service quality, and producing sustainable operating margins become increasingly difficult as the portfolio grows. If Dwelly can demonstrate that automation materially improves the economics of traditional letting agencies, however, it could provide a blueprint for applying AI to other fragmented service industries where much of the work remains manual.
Funding Details
Startup: Dwelly
Investors: Not publicly disclosed
Amount Raised: $170 million
Total Raised: Not publicly disclosed
Funding Stage: Series B
Funding Date: August 2026
Headquarters: London, United Kingdom
Sector: Proptech / Real Estate Marketplace
What Today’s Funding Activity Reveals
Taken together, these funding rounds expose some emerging patterns in the global tech ecosystem:
-
Infrastructure Over Apps. The bulk of capital is moving into physical and systems infrastructure – AI hardware, energy storage, satellites, even a new bank – rather than consumer apps. Investors are signaling that foundational layers (compute, power, defense hardware, specialized finance) are the bottlenecks to the next growth wave. For example, Lumilens (AI photonics), Base Power (grid batteries) and CFS (fusion plant) all fit this thesis. Founders targeting core infrastructure stand to benefit from this funding climate – but must deliver accordingly.
-
AI as Force Multiplier (and Threat). AI is both a magnet for investment and a driving force behind new threats. Whatnot’s round was fueled partly by AI-based seller tools and the promise of AI-assisted livestreaming sales. Corma’s raise reflects fear of AI-powered cyberattacks. Lumilens addresses AI’s insatiable compute needs. In each case, AI is the context: investors either back AI-enabled solutions or technologies (like high-speed networking) that enable AI. This bifurcation – AI as promise vs. AI as peril – will define many deals going forward.
-
Investor Concentration. Many rounds involve repeat or overlapping investors. DFJ Growth’s play in Cambridge Aerospace (and its Anduril ties) mirrors Lux/Andreessen/etc. in Erebor and Whatnot. A handful of top-tier firms (Sequoia, Iconiq, a16z, Ribbit, etc.) appear in multiple deals, reflecting concentrated risk-taking. For founders, this means networking with one lead often unlocks additional leads; for others, it may raise the bar to secure fresh pockets of capital.
-
Geographic Spread. While US and UK companies dominate the list, we see a global tilt. Corma (Israel/US), Cambridge Aerospace (UK), Erebor (US/UK in investor mix), Dwelly (UK), CFS (US), and Sierra (US) – most are Western. One Asian-adjacent note: Erebor’s banking angle heavily favors the US tech and defense market. (Notably, no large China or India rounds in this brief window; Asia’s funding climate remains more cautious. Past quarters have shown funds pulling back from big China deals.) The pattern suggests hot-money regions remain the US and EU for now.
-
Capital Efficiency vs. Scale. Some raises (Cambridge, Base Power, CFS) are follow-ons to prior rounds within months, emphasizing explosive growth or runway extension. Others (Whatnot, Sierra Space) fund international scaling or capacity build-out. Founders need to justify the usage: are you spending to scale fast, or to capture a narrow market before competition? The fact that extremely large rounds are happening in sectors like drone defense and batteries indicates investor faith in long-term global demand; smaller “Me-too” tech startups may find it hard to compete without a unique angle.
Venture Funding Table
| Startup | Amount Raised | Sector | Stage | Lead Investors | Country |
|---|---|---|---|---|---|
| Cambridge Aerospace | $300M | Defense tech (counter-drone) | Series C | DFJ Growth (lead), Lux, Accel, Lakestar, others | UK |
| Lumilens | $700M | AI hardware / optical interconnects | Series C | Atreides, Bain Capital, Meritech, Seligman, Spark (co-leads); plus Addition, Qualcomm Ventures, etc. | USA (CA) |
| Whatnot | $545M | Live-commerce marketplace | Series G | ICONIQ, Lightspeed, Avra (co-leads) | USA (CA) |
| Base Power | $1B | Energy storage (home batteries) | Series D | Ribbit, Addition, Valor Equity, JPMorgan Strategic | USA (TX) |
| Commonwealth Fusion Sys | $1B | Clean energy (fusion) | Late-stage | Institutional investors (pension, SWFs, industrial) | USA (MA) |
| Sierra Space | $550M | Space/defense technology | Series C | LuminArx (lead), General Atlantic, Coatue, others | USA (CO) |
| Dwelly | $170M | Proptech / rental marketplace | Series B | Undisclosed | UK (London) |
| Erebor (bank) | $1.5B (rumored) | Fintech/startup bank | Growth | Lux, a16z, Valor, H/CAP, etc. (expected) | USA (OH) |
| Corma | $60M | Cybersecurity (AI defense) | Seed | Sequoia (lead), Khosla Ventures, Coatue | ISR/USA |
| Antora Energy | $550M | Clean energy (thermal batteries) | Series C | G2 Venture Partners, Eclipse (co-leads) | USA (CA) |
Strategic Takeaways for Founders and Investors
-
Founders (product focus): Emphasize defensibility in critical infrastructure. Whether it’s a photonics chip or a battery system, highlight how your tech solves an impossible-to-avoid problem for big customers (governments, telcos, utilities). Demonstrate early customer traction with demonstrable metrics (e.g. battery megawatt-hours in service, military orders, model accuracy). Founders should also show capital discipline: these large rounds come with expectations of capital efficiency. For AI startups, pairing with domain expertise (security, engineering) is a must. If you’re in a crowded space, articulate a niche where speed or cost matters (as Cambridge did vs. expensive interceptors).
-
Founders (finance/valuation): Current deals are setting new price benchmarks. If you’re raising in this environment, be aware that money still chases technical differentiation, but at the price of very high valuations. Founders can afford to be choosy with investor terms since VCs are competing to get in on these themes. However, the unwritten expectation is that you deliver extraordinarily high growth or key milestones post-fundraise. For example, Lumilens and CFS are essentially funded to execute on well-defined roadmaps; the capital is for scale and proving tech viability. Plan accordingly: have clear use of proceeds and short-term milestones to show the raise is more than just a bigger war chest.
-
Investors: Today’s rounds confirm that you should continue concentrating on capital-intensive innovation in climate, defense and data infrastructure. Those sectors have momentum backed by both market demand and government support (e.g., defense grants, climate subsidies). For VCs, the job is to judge who can not only build the product but also secure the technical compliance and ecosystem partnerships (e.g. with utilities or armed forces) needed. Also, note the recurring participation of crossover and mega-funds – their involvement signals where liquidity might eventually arise (if any) or where infrastructure co-investors will follow.
-
Market Signals: The fact that many of these rounds were co-led by prominent growth investors (e.g. DFJ, Sequoia, Iconiq, LuminArx) signals that the “steady return, low churn” playbook still works. Investors are betting on long-term secular shifts (AI requires massive new networks; carbon policy will subsidize grid tech; national security will underwrite defense startups). However, they’re also aware of the uneven backdrop: consumer tech and crypto are quiet, so allocations are skewed toward these industrial / B2B outliers. Founders and analysts should view today’s deals as part of a bifurcated market: software rounds below $50M are hard to come by outside AI, but capital is abundant for visionary deep-tech ideas.
-
Risk and Defense: A side lesson is risk perception. AI doubling times and the rise of autonomous threats have magnified perceived tail risks in certain domains (cyberattack escalation, grid instability, drone warfare). Founders addressing risk mitigation (cyber defense, energy backup, physical security) can command as much attention as those enabling rapid growth. Investors’ checkbooks reflect a “kill chain” mentality – invest in both the attack and the defense.
Conclusion
Monday’s mega-rounds paint a picture of an ecosystem circling key infrastructure plays. Capital is pouring into the technologies that undergird AI, security and energy: from batteries in your garage to lasers in orbital factories. The trend suggests the venture world is both protective and opportunistic: protecting critical systems from failure (or attack), and positioning ahead of massive shifts (like AI-driven cloud scale). For startup founders, the message is that solving “core” problems at scale can still unlock outsized funding, even in a quieter VC environment. For investors, today’s deals confirm a thesis: real-world needs (defense, resilience, power) can override short-term market jitters.
In summary, expect venture capital to continue clustering around big, systemic challenges – the planet’s power grids, national defense grids, and even the “plumbing” of AI itself – more than around flashy consumer apps. Where the work involves hard science or heavy hardware, the VC market is back with checkbooks. The startup world’s next chapter may very well be about rebuilding and reinforcing the foundations of the digital age, not just chasing the next trend.