Venture Capital & Startup Funding Roundup, September 9, 2026: Coatue, Andreessen Horowitz, Greylock, Kleiner Perkins, Sequoia & More
 Nickie Louise
Posted On September 9, 2026

Venture capital’s center of gravity today isn’t in one neat category called AI. It is moving toward companies that control high-value workflows: legal work, sales, wealth management, cybersecurity, industrial production and even weather-risk operations. The ten most consequential rounds verified inside the past twelve hours total roughly $1.47 billion, with about 91% of that capital concentrated in the six largest financings. That distribution is telling: investors are still willing to write very large checks, but mostly where they see a path to owning an operational system rather than selling a thin feature on top of somebody else’s model.
The biggest signal came late in the research window. Legal AI company Harvey announced a fresh $550 million round at a $15.5 billion valuation, while Lightfield surfaced with a $47 million Andreessen Horowitz-led Series A aimed directly at rebuilding customer relationship management for an agent-driven software era. Between those two poles sit a $245 million cybersecurity financing for Cylake, an unusually large $225 million Series A for Solstice Oncology, and triple-digit rounds for Clay, Perry Weather and Savvy Wealth.
The Macro Environment: Capital Is Moving From Models to Operational Control
The venture market is drawing an increasingly sharp distinction between companies that merely use artificial intelligence and those that can turn it into a durable system of record, execution or infrastructure. Harvey is becoming an operating layer for legal work; Clay and Lightfield are competing to control customer data and revenue workflows; Euno wants to supply the organizational context that autonomous agents need; CloudNC brings AI into CNC machining. These are not ten variations of a chatbot. They are attempts to insert software into processes where errors are expensive, data accumulates over time, and switching costs can become substantial.
That helps explain the check sizes. Investors appear increasingly comfortable funding AI applications at infrastructure-like valuations when those applications sit directly in the flow of work. Harvey has gone from an $8 billion valuation in December 2025 to $11 billion in March and now $15.5 billion in September. Clay, meanwhile, has more than doubled its valuation from $3.1 billion in August 2025 to $7.1 billion today. The market is effectively saying that a small number of application companies may become very large platforms if they own proprietary workflow data, distribution, and execution rather than relying solely on model differentiation.
The public-market backdrop is supportive but not indiscriminate. Barclays raised its 2026 S&P 500 target on strong corporate earnings and continued AI spending, while simultaneously warning about demanding valuations, persistent inflation, geopolitical risk and a more hawkish rate environment. That combination helps explain why private capital is concentrating rather than spreading evenly: when the cost of being wrong remains high, investors gravitate toward category leaders, clear enterprise budgets, technically differentiated security products and software connected to measurable operating outcomes.
Secondly, a less visible thread running through today’s deals: the digitization of physical and regulated operations. Perry Weather sells safety and weather-operations software; WINT addresses water management; CloudNC automates precision machining; Solstice is applying venture-scale capital to immunotherapy development. Capital is not abandoning software. It is expanding software’s addressable territory into sectors where operational data, regulation, physical assets, or scientific risk create stronger barriers to entry than a generic AI interface can provide.
Top Funding Rounds
Harvey raises $550 million to turn legal AI into an enterprise operating layer
Harvey is the day’s largest qualifying round and arguably its clearest valuation signal. The San Francisco legal AI startup raised $550 million at a $15.5 billion valuation, with new investors Diffusion and Lightspeed Venture Partners co-leading. Existing investors, including Sequoia, Kleiner Perkins, Andreessen Horowitz, Coatue, Conviction, GIC, and Goldman Sachs Alternatives, also participated. Harvey builds AI software for law firms and corporate legal departments, covering contract analysis, due diligence, compliance, and litigation workflows.
Why does a vertical-software company need this much capital? Harvey increasingly behaves less like conventional SaaS and more like an applied AI platform. The company says it will put the financing into model training, product expansion and international hiring, and it also announced the acquisition of agent-security startup Guardrails AI — Harvey’s fourth acquisition this year. Its valuation has risen from $11 billion in March to $15.5 billion now, a roughly 41% step-up in less than six months. Reuters reported in March that Harvey had already raised more than $1 billion; adding today’s round takes disclosed cumulative funding above $1.55 billion.
The competitive implication extends well beyond legal tech. Harvey demonstrates that application-layer companies can command model-company-style financing when investors believe the application owns valuable data, domain-specific evaluation, customer relationships and the workflow itself. The risk is equally clear: at $15.5 billion, Harvey must grow into a much larger revenue base while competing with specialist rivals such as Legora and Clio, as well as broader AI platforms entering professional services. Reuters noted that Harvey is already used by 80% of the 100 highest-grossing U.S. law firms, giving investors evidence that distribution is becoming a genuine barrier rather than a theoretical one.
Funding Details
Startup: Harvey
Investors: Diffusion, Lightspeed Venture Partners, Sequoia, Kleiner Perkins, Andreessen Horowitz, Coatue, Conviction, Elad Gil, Evantic, GIC, Goldman Sachs Alternatives, Verified Capital, WNDR, Sapphire Ventures, Whale Rock
Amount Raised: $550 million
Total Raised: More than $1.55 billion based on disclosed funding
Funding Stage: Growth financing; round label not disclosed
Funding Date: September 9, 2026
Headquarters: San Francisco, California
Sector: Legal AI / Enterprise Software
Cylake raises $245 million to build a cybersecurity platform for operational sovereignty
Cylake raised $245 million in convertible notes from Lightspeed Venture Partners, Picture Capital and Redpoint Ventures. Axios describes the Sunnyvale company as building a cybersecurity platform for “operational sovereignty,” while the funding announcement says Cylake is approaching the beta release of its next-generation security product.
The most interesting part of the deal is not simply its size but its structure. A $245 million convertible-note financing ahead of broad product disclosure gives investors exposure while postponing the valuation mechanics that normally accompany a priced venture round. That is unusually substantial optionality capital for a cybersecurity company at this point in its public life. It suggests Lightspeed, Picture and Redpoint see a potential platform opportunity large enough to justify funding ahead of clearer commercial benchmarks.
A broader security thesis is embedded here. As companies deploy autonomous software into production, cybersecurity increasingly has to protect not just networks and identities, but an organization’s ability to keep operating when software, agents, credentials, or infrastructure are compromised. Cylake has not yet disclosed enough publicly to judge how differentiated its architecture will be, so view the financing primarily as a strong investor signal rather than proof of product-market leadership. The large convertible structure also makes valuation conclusions premature.
Funding Details
Startup: Cylake
Investors: Lightspeed Venture Partners, Picture Capital, Redpoint Ventures
Amount Raised: $245 million
Total Raised: Not disclosed
Funding Stage: Convertible-note financing
Funding Date: September 9, 2026
Headquarters: Sunnyvale, California
Sector: Cybersecurity / Operational Resilience
Solstice Oncology launches with $225 million in funding to advance next-generation cancer immunotherapy
Solstice Oncology launched with a $225 million Series A led by RA Capital Management, joined by Canaan Partners and Forbion. The Boston biotech is focused on a second-generation CTLA-4 immunotherapy program and is associated with Harbour BioMed, which announced the financing for its partner company.
A $225 million Series A is notable even by biotech standards. It shows that while general venture markets are concentrating around AI, specialist life-sciences funds remain willing to assemble very large syndicates at company formation when the therapeutic thesis and development path justify it. RA Capital, Canaan and Forbion are not funding a broad software-style experimentation cycle; they are funding clinical development where capital requirements arrive early, and failure can be binary.
Strategically, Solstice also illustrates why biotechnology has not been displaced by the AI funding boom. Software can often reach market with progressively larger rounds. Drug companies may need hundreds of millions before commercial validation because clinical programs, manufacturing, regulatory work, and trials are expensive. Investors therefore care less about early revenue and more about the quality of the biological hypothesis, translational evidence, and the probability that a differentiated therapy can improve on existing treatment approaches. Solstice’s financing places it among the best-capitalized new oncology companies to emerge this year.
Funding Details
Startup: Solstice Oncology
Investors: RA Capital Management, Canaan Partners, Forbion
Amount Raised: $225 million
Total Raised: At least $225 million disclosed
Funding Stage: Series A
Funding Date: September 9, 2026
Headquarters: Boston, Massachusetts
Sector: Biotechnology / Oncology / Immunotherapy
Clay raises $115 million to expand AI-driven sales and marketing automation
Clay raised $115 million in a Series D at a $7.1 billion valuation, led by Wellington Management. Reuters reported participation from Sequoia, StepStone, Andreessen Horowitz and Perennial; Axios also reported participation from a16z, Sequoia, DST Global and CapitalG. Clay develops sales and marketing software that uses AI agents to analyze company and customer data, recommend actions and execute parts of go-to-market workflows. Customers include Google and Anthropic.
The valuation is the bigger story. Clay was valued at $3.1 billion in an August 2025 financing. Today’s $7.1 billion price means investors have more than doubled the mark in roughly thirteen months. That re-rating implies the market believes AI-native revenue software can take meaningful share from older sales-tech stacks rather than merely supplement them.
Clay sits in one of the most contested application categories in technology. Salesforce, HubSpot, and a long list of prospecting and sales-intelligence vendors already command enterprise budgets, while new startups can access increasingly similar foundation models. Clay’s defense therefore has to come from workflow depth, integrations, proprietary customer data, user adoption, and the ability to turn fragmented sales information into actions. The funding gives it more capacity to build those advantages, but the $7.1 billion valuation sharply raises the growth expectations attached to them.
Funding Details
Startup: Clay
Investors: Wellington Management, Sequoia Capital, Andreessen Horowitz, StepStone, Perennial; Axios also reports DST Global and CapitalG
Amount Raised: $115 million
Total Raised: Not disclosed in the current announcement
Funding Stage: Series D
Funding Date: September 9, 2026
Headquarters: New York, New York
Sector: Enterprise AI / Sales Technology
Perry Weather raises $110 million in funding to scale automated weather safety operations
Dallas-based Perry Weather secured a $110 million growth investment led by Silversmith Capital Partners, with existing investor Arthur Ventures participating. Same-day deal tracking identifies the financing as a Series C. Perry provides weather-monitoring, operations, and safety software designed to help organizations make operational decisions around weather risk.
This is an easy deal to overlook beside legal AI or cybersecurity, but it reflects a durable venture theme: software is moving deeper into physical operations. Weather is not simply a forecasting problem for customers that manage outdoor workforces, facilities, sports, construction or other exposed assets; it can become a safety, liability and scheduling problem. That converts meteorological information into an operational budget rather than a consumer-information product.
Silversmith’s participation is also informative. The growth investor has publicly emphasized capital-efficient technology businesses serving identifiable customer needs, and Perry fits that pattern better than a research-heavy AI bet. The investment suggests that investors still see considerable value in vertical software categories where domain specialization, embedded workflows and customer retention can matter more than model novelty.
Funding Details
Startup: Perry Weather
Investors: Silversmith Capital Partners, Arthur Ventures
Amount Raised: $110 million
Total Raised: Not disclosed in the current announcement
Funding Stage: Series C / Growth financing
Funding Date: September 9, 2026
Headquarters: Dallas, Texas
Sector: Weather Technology / Operational Safety Software
Savvy Wealth raises $100 million to build an AI-enabled operating platform for independent advisers
Savvy Wealth raised an oversubscribed $100 million Series C at a $600 million valuation, led by Halo Fund. Thrive Capital, Industry Ventures, Canvas Prime, Index Ventures, The House Fund, Euclidean Capital, Allianz Life, Alumni Ventures and Vestigo Ventures participated. The financing takes Savvy’s disclosed capital raised to $200 million.
The valuation progression is striking. In July 2025, the Financial Times reported that Savvy had raised $72 million at a $225 million valuation. A little over a year later, the company is priced at $600 million. Savvy says more than 150 advisers now use its platform, that its technology consolidates more than 20 vendors, and that advisers save an average of 19 hours per week. Those figures are company-reported, but they help explain the investor thesis: the product is trying to turn fragmented wealth-management administration into a unified operating stack.
Savvy is also part of a broader convergence between venture capital and private-equity-style operating models. The FT previously reported that Savvy’s capital was being used both for technology and to acquire or recruit advisers, one example of venture firms applying software and AI to established service industries. That model can be powerful because the software has an immediate distribution channel, but it needs to prove that technology meaningfully improves economics rather than simply subsidizing asset gathering.
Funding Details
Startup: Savvy Wealth
Investors: Halo Fund, Thrive Capital, Industry Ventures, Canvas Prime, Index Ventures, The House Fund, Euclidean Capital, Allianz Life, Alumni Ventures, Vestigo Ventures
Amount Raised: $100 million
Total Raised: $200 million
Funding Stage: Series C
Funding Date: September 9, 2026
Headquarters: New York, New York
Sector: Wealthtech / Financial Adviser Infrastructure
Valuation: $600 million
Lightfield raises $47 million to challenge traditional CRM with an AI-native system of record
Lightfield announced a $47 million Series A led by Andreessen Horowitz, with Maverick Capital, Coatue Management, Greylock, Lightspeed, Audacious Ventures and Alumni Ventures participating. Founder Keith Peiris says more than 5,000 companies have signed up since Lightfield launched last November. The company is building an AI-native customer system that continuously draws context from interactions rather than relying solely on workers manually updating database fields.
This round arrived only about two hours before the research cutoff, making it one of the freshest deals in today’s cohort. It is also one of the more strategically interesting. Traditional CRM systems were designed around human-entered records; autonomous software needs richer context, provenance, history, and permissions to act reliably. Lightfield bets that this architectural difference is large enough to support an entirely new system of record rather than another agent layered on Salesforce.
The investor syndicate shows how seriously venture firms are taking that possibility. Andreessen Horowitz is joined by firms that have extensive enterprise-software experience, while Greylock and Lightspeed are also active elsewhere in the AI stack. Yet this category will be unforgiving. Clay, Salesforce, HubSpot, Attio, and numerous AI-native entrants are all chasing portions of the same revenue-operations budget. Lightfield therefore needs its accumulated customer context to become more valuable over time; otherwise, foundation-model improvements could compress differentiation.
Funding Details
Startup: Lightfield
Investors: Andreessen Horowitz, Maverick Capital, Coatue Management, Greylock Partners, Lightspeed Venture Partners, Audacious Ventures, Alumni Ventures, additional founder-investors
Amount Raised: $47 million
Total Raised: Not disclosed in the announcement
Funding Stage: Series A
Funding Date: September 9, 2026
Headquarters: United States
Sector: Enterprise AI / CRM / Revenue Software
WINT raises $36 million in funding to expand intelligent water management
WINT raised $36 million in Series D financing led by LIP Ventures and Inven Capital. Axios describes the company as a provider of water-management intelligence, positioning it at the intersection of climate technology, building operations and risk management.
The deal is small relative to Harvey or Solstice, but its economics may be easier to understand than many AI application bets. Water leaks and inefficient consumption produce direct costs, property risk and insurance exposure. Software capable of detecting, analyzing and reducing those losses can therefore sell against quantifiable operational spending rather than a speculative innovation budget.
That distinction matters in a venture market where investors are asking harder questions about return on AI expenditure. Climate software tied to measurable resource use can demonstrate value without relying on customers to believe a broad transformation story. The Series D stage also indicates WINT is being financed as a scaling business, not an early technology experiment.
Funding Details
Startup: WINT
Investors: LIP Ventures, Inven Capital
Amount Raised: $36 million
Total Raised: Not disclosed in the current announcement
Funding Stage: Series D
Funding Date: September 9, 2026
Headquarters: New York, New York, as reported by Axios
Sector: Climate Technology / Water Intelligence
Euno raises $23 million to build the context layer for enterprise AI agents
Euno raised a $23 million Series A led by N47, bringing total funding to $29 million. Existing investor 10D participated alongside founders and executives associated with Wiz, Cyera, Eon, Tavily, and Tableau. Euno operates from San Francisco and Tel Aviv and is developing an enterprise “context” platform intended to reconstruct how organizational data is defined and used so AI systems can make decisions with the same institutional knowledge available to employees.
The company is tackling one of enterprise AI’s less glamorous but more persistent problems: models may be able to reason over data without knowing which internal definition, metric, table, or business rule is authoritative. Companies have spent decades accumulating inconsistent schemas and undocumented assumptions. Euno’s pitch is that an AI agent needs this organizational context before it can be trusted to act autonomously across enterprise data.
That puts Euno in a potentially valuable layer between models and enterprise systems, but also in a crowded part of the stack. Data platforms, catalog vendors, semantic-layer providers, and model companies are all moving toward richer context management. The investment case therefore depends on whether Euno can become a persistent knowledge layer that improves as agents work, rather than a feature that larger data platforms can replicate.
Funding Details
Startup: Euno
Investors: N47, 10D, and technology-founder investors
Amount Raised: $23 million
Total Raised: $29 million
Funding Stage: Series A
Funding Date: September 9, 2026
Headquarters: San Francisco, California and Tel Aviv, Israel
Sector: Enterprise AI / Data Infrastructure / Agent Context
CloudNC raises $20 million in funding to bring AI into CNC manufacturing
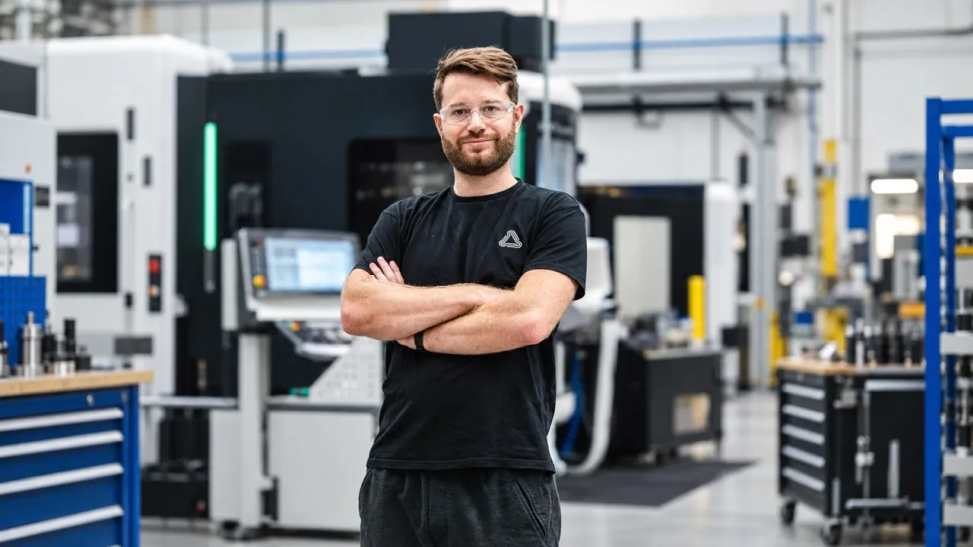
London-based CloudNC raised $20 million in funding led by Nimble Ventures, with Calculus Venture Capital, Entrepreneur First and LM Ventures, Lockheed Martin’s venture arm, participating. CloudNC builds precision-machining software; its CAM Assist product uses AI to reduce the time required to devise CNC machining strategies and generate toolpaths. The company says more than 1,000 machine shops worldwide use its technology, including hundreds in the United States.
This is one of the day’s smaller rounds but one of the clearest examples of AI entering the industrial base. CNC programming is specialized work embedded in aerospace, automotive, defense, and advanced manufacturing supply chains. Reducing programming time can directly affect quoting speed, machine utilization, and manufacturing throughput. CloudNC is also developing an automated Quote Agent and working toward FedRAMP compliance with Knox Systems, an indication that U.S. government and defense-related use cases are part of its expansion strategy.
Lockheed Martin’s participation adds strategic weight. The opportunity is not simply to sell AI software to factories; it is to reduce a bottleneck in producing precision components at a time when the U.S. and Europe are spending heavily on defense manufacturing and supply-chain capacity. CloudNC therefore fits a wider “industrial AI” thesis in which software enhances existing machine infrastructure rather than requiring manufacturers to rebuild plants around entirely new robotics systems.
Funding Details
Startup: CloudNC
Investors: Nimble Ventures, Calculus Venture Capital, Entrepreneur First, LM Ventures
Amount Raised: $20 million
Total Raised: Not disclosed in the current announcement
Funding Stage: Not disclosed
Funding Date: September 9, 2026
Headquarters: London, United Kingdom
Sector: Industrial AI / Precision Manufacturing / Developer Tools for CNC
What Today’s Funding Activity Reveals
The first pattern is extreme capital concentration. These ten rounds represent about $1.47 billion, but Harvey, Cylake, Solstice, Clay, Perry Weather, and Savvy Wealth alone account for roughly $1.35 billion, or about 91% of the sample. Venture capital may be active, but it is not behaving democratically. The largest pools of money are going to companies investors believe can become category-defining platforms, companies with unusually high technical or regulatory development costs, or companies already demonstrating strong enterprise distribution.
Second, the application layer is becoming more important, not less. Early generative-AI investing centered heavily on models, chips, and compute. Today’s rounds show capital moving into the systems that decide where AI actually gets used: Harvey in legal work, Clay and Lightfield in revenue operations, Savvy in wealth management, Euno in enterprise data, and CloudNC in machining. Investors appear to be betting that the companies capturing proprietary workflow context can preserve pricing power even as access to capable models becomes cheaper and more interchangeable.
Third, “AI defensibility” is shifting from the model to the data-and-workflow loop. Lightfield wants every customer interaction to improve its representation of a business. Euno wants organizational context to accumulate as agents use enterprise data. Harvey sits inside legal work where auditability, institutional knowledge, and domain-specific behavior matter. Clay sits in go-to-market operations where enrichment, integrations, and customer history can create a compounding dataset. That is a more credible source of differentiation than simply calling a third-party model through an API.
Fourth, venture capital remains heavily U.S.-centered even in a global search. Eight of the ten selected companies are headquartered in the United States, based on the locations reported in today’s coverage; Euno has a dual U.S.-Israel presence, while CloudNC is based in London. The imbalance is especially visible in large rounds. Harvey, Cylake, Solstice, Clay, Perry Weather and Savvy account for nearly all of the capital in the sample and are all U.S.-headquartered.
Finally, software and the physical economy are converging. Weather risk, water management, and machining are receiving institutional venture checks because software increasingly drives real-world operational decisions. The implication is that the next generation of valuable “AI companies” may not look like conventional AI startups. They may look like manufacturing software, compliance infrastructure, safety systems, or vertical operating platforms whose machine intelligence is largely invisible to the end user.
Comparative Funding Table
| Startup | Amount Raised | Sector | Funding Stage | Lead Investors | Country |
|---|---|---|---|---|---|
| Harvey | $550M | Legal AI | Growth financing | Diffusion, Lightspeed Venture Partners | United States |
| Cylake | $245M | Cybersecurity | Convertible notes | Lightspeed, Picture Capital, Redpoint | United States |
| Solstice Oncology | $225M | Biotechnology / Oncology | Series A | RA Capital Management | United States |
| Clay | $115M | AI Sales Software | Series D | Wellington Management | United States |
| Perry Weather | $110M | Weather / Safety Software | Series C | Silversmith Capital Partners | United States |
| Savvy Wealth | $100M | Wealthtech | Series C | Halo Fund | United States |
| Lightfield | $47M | AI / CRM | Series A | Andreessen Horowitz | United States |
| WINT | $36M | Water Intelligence | Series D | LIP Ventures, Inven Capital | United States |
| Euno | $23M | Enterprise AI / Data | Series A | N47 | United States / Israel |
| CloudNC | $20M | Industrial AI / Manufacturing | Not disclosed | Nimble Ventures | United Kingdom |
Strategic Takeaways for Founders and Investors
For founders, today’s strongest message is that “AI-powered” is no longer an investment thesis on its own. Companies attracting premium capital can explain why their position strengthens as models improve. Harvey owns legal workflows and distribution. Lightfield wants to own customer context. Euno is building organizational context for agents. CloudNC embeds intelligence in specialized manufacturing processes. The common thread isn’t the model; it is the system around it.
That puts pressure on founders to identify a source of defensibility that survives model commoditization. Proprietary data can help, but only when itis hard to recreate and tied to repeated customer activity. Workflow ownership is stronger when the product becomes part of how decisions are made. Distribution matters when customers trust the platform with high-stakes tasks. Regulatory knowledge matters when compliance limits the number of credible vendors. Hardware or industrial integrations matter when deployment requires real-world engineering rather than a browser interface. Today’s rounds reward several of those characteristics.
The second lesson is about pricing and valuation discipline. Harvey at $15.5 billion and Clay at $7.1 billion show that late-stage investors are again willing to pay aggressively for perceived winners. But those valuations are not free capital. They set much higher exit thresholds and put pressure on sustained revenue growth. Harvey’s valuation has risen from $8 billion in December to $11 billion in March and $15.5 billion today; Clay has moved from $3.1 billion last August to $7.1 billion. For founders considering large step-ups, the relevant question is not whether investors will pay the number, but whether the company can grow into it without making the next financing strategically restrictive.
The third lesson is that investors are increasingly willing to fund capital intensity when it’s inherent to the opportunity. Solstice needs a large Series A because drug development is expensive. CloudNC is attacking slow-moving industrial systems. Cylake has raised an unusually large convertible financing before broad product rollout. The market is not demanding capital efficiency in a simplistic “spend less” sense; it is demanding a credible relationship between capital consumed and strategic position created.
For investors, the most interesting opportunities may increasingly sit below the foundation-model layer. As access to leading models broadens, economic value can migrate toward companies that own the customer relationship and can decide which model to use for a given job. Enterprise context, security, orchestration, vertical data and physical-world execution all provide ways to capture that value. The risk is that many such businesses will prove to be features rather than independent platforms. The investor’s job is therefore to distinguish companies that merely package AI from those accumulating durable control over data, distribution and execution.
And the geography offers a useful warning. Today’s funding cohort is overwhelmingly U.S.-weighted even after a global search. Europe contributes CloudNC and part of Euno’s operating footprint, but the biggest application-software rounds remain clustered around San Francisco, New York, Boston, Dallas and Silicon Valley. For non-U.S. founders, that reinforces the importance of selling into American enterprise budgets early; for investors, it suggests that some of the more mispriced opportunities may lie in technically strong ecosystems where financing remains less abundant.
Conclusion
Today’s venture activity is a useful snapshot of where the startup market is heading after several years in which “AI” itself was enough to command attention. Capital is becoming more specific. Investors are asking which company owns the workflow, which one accumulates proprietary context, which one can prove customer value, and which one sits in a part of the economy where replacement is genuinely difficult.
Harvey’s $550 million round is the headline, but the more revealing story is the breadth underneath it. Legal work, cybersecurity, oncology, sales, wealth management, weather operations, water systems, enterprise data and CNC machining all attracted fresh capital within the same twelve-hour window. The common denominator is not industry. It is investors’ willingness to finance software and science that sits close to high-value decisions and hard operational problems.
That points toward a more mature phase of the current technology cycle. Foundation models remain economically important, but increasingly they are becoming inputs into larger businesses. The next enduring venture franchises may be built by companies that make those models useful inside legal departments, factories, advisory firms, security teams, and other environments where context, trust, and execution matter more than benchmark scores.
For founders, that is a demanding message but a constructive one: access to advanced AI is becoming common. Owning a problem that customers cannot afford to leave unsolved is becoming scarce.