These 10 Types of Startups Are Disappearing as AI Turns Their Products Into Features
 Daniel Levi
Posted On September 8, 2026

In February 2025, Chegg sued Google, blaming the tech giant’s AI-generated search summaries for losing traffic as the online education company struggled with falling revenue and a stock price that had already lost roughly 99% from its 2021 peak.
A year later, Chegg looks less like an isolated casualty and more like a canary in the coal mine.
The company’s revenue fell 39% in 2025. Fourth-quarter revenue plunged 49%. By the second quarter of 2026, revenue had fallen another 51% from a year earlier. Chegg itself has pointed to free AI products and Google’s AI Overviews as part of the pressure on a business once built around something students were willing to pay for: answers.
Chegg’s problem is now spreading far beyond education.
AI is not simply creating a new generation of startups. It is eroding the economics of an older one, turning products that once justified entire companies into features bundled inside Google Workspace, GitHub, Adobe Acrobat, Apple Photos, and general-purpose AI assistants.
The pattern is becoming hard to miss:
2019: That’s a startup.
2023: That’s an AI startup.
2026: That’s a button.
That does not mean every startup in the categories below is dying. Some are thriving by moving up the stack and selling deeper workflows, proprietary data, infrastructure, or business outcomes. What is disappearing is something narrower: the ability to build a defensible standalone business around a basic task that AI can now perform cheaply, instantly, or as part of something customers already pay for.
Dead on Arrival: 10 Startup Ideas AI Is Turning Into Commodities
Before getting into the numbers, it helps to look at the bigger pattern. AI is pressuring a broad class of startups whose core product is a task frontier models can increasingly perform directly. Some are already showing measurable declines. Others are being forced to move beyond the basic feature as that capability becomes cheaper, bundled, or free.
The most exposed categories include:
- AI wrapper startups — thin interfaces around frontier models with little proprietary technology or differentiation.
- Generic copywriting startups — basic blog posts, product descriptions, ad copy, and SEO content are becoming inexpensive to generate with general-purpose AI.
- Traditional translation startups — particularly commodity text translation rather than specialized, legal, or localization work.
- Basic transcription startups — speech-to-text has become cheap enough to move from a standalone product toward a built-in feature.
- Stock-image startups — generative imagery attacks the scarcity at the heart of the traditional search-and-license model.
- Resume and cover-letter startups — millions of users can now ask a general-purpose AI assistant to create or rewrite application materials directly.
- Basic chatbot startups — generic customer-support chat is increasingly becoming a feature inside larger AI and enterprise software platforms.
- Simple meeting-note startups — transcription, summarization, and action-item extraction are increasingly bundled into broader productivity suites.
- Commodity coding-assistant startups — basic code generation and autocomplete are becoming free or heavily subsidized, putting pressure on products with little differentiation beyond the underlying model.
- Basic research and summarization startups — summarizing documents, answering questions about files, and synthesizing routine information are increasingly native capabilities of frontier AI platforms.
The important distinction is that exposure does not mean extinction. Some companies in these categories are growing quickly because they have moved beyond the basic task into workflows, proprietary data, infrastructure, distribution, or specialized outcomes.
The evidence tells us where that dividing line is starting to appear.
Here are 10 types of startups where that shift is already underway, ranked by evidence strength.
1. Paid homework-answer and textbook-solution startups
What they used to sell: Students paid for access to libraries of worked answers, textbook solutions, and explanations that were difficult or time-consuming to find elsewhere. Chegg built a massive subscription business around that model.
Why they are disappearing: General-purpose AI assistants can answer a question, explain each step, respond to follow-up questions, and adapt the explanation to the student. That weakens the value of paying separately for access to a static answer library. AI-generated answers in search create a second problem by intercepting students before they reach the website.
Hard evidence: Chegg generated $376.9 million in revenue in 2025, down 39% from the previous year, while fourth-quarter revenue fell 49% to $72.7 million. The deterioration continued in 2026. Second-quarter revenue dropped 51% year over year to $51.8 million, while Academic Services revenue plunged 61% to $34.3 million.
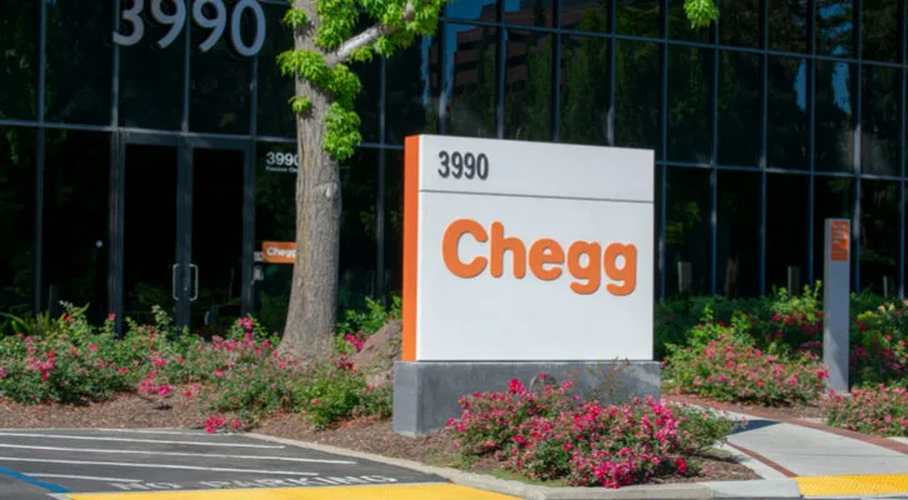
The connection to AI is unusually explicit. In Q2 2025, Chegg said it had 2.6 million subscribers, down 40% year over year, as it continued to feel the impact of lower traffic “largely due to Google AI Overviews.”
AI replacement: ChatGPT and other general-purpose AI assistants can provide interactive explanations, while Google AI Overviews can answer some questions without requiring students to leave search.
Counterpoint: Chegg is not dead. It is reinventing itself around workforce skilling, where Q2 2026 revenue actually grew 2%. The lesson is narrower: charging for basic access to answers has become a much harder business.
2. Search-dependent answer-content startups
What they used to sell: These companies turned routine questions, explainers, definitions, and how-to content into traffic, then monetized those visitors through advertising, affiliate links, subscriptions, or lead generation.
Why they are disappearing: AI search attacks the economic transaction at the model’s center. If the search engine answers the question directly, the user may never visit the website that created or organized the information.
Hard evidence: A 2025 Pew Research Center study of 68,879 Google searches found users clicked a traditional search result on 8% of visits where an AI summary appeared, compared with 15% when one did not. Links cited inside AI summaries received clicks on just 1% of visits containing a summary.
Ahrefs later analyzed 300,000 keywords and estimated that AI Overviews were associated with a 58% reduction in click-through rates for the top-ranking result compared with its counterfactual model.
AI replacement: Google AI Overviews and other answer engines increasingly resolve informational queries directly on the results page.
Counterpoint: Lower click-through is not the same as startup failure. Original reporting, communities, proprietary data, direct audiences, and useful tools still give people reasons to visit a website. The greatest exposure is in interchangeable content whose entire value can be captured in a short AI answer.
3. Commodity illustration and image-production marketplaces
What they used to sell: Customers commissioned simple illustrations, marketing graphics, and promotional assets through online marketplaces or managed creative services. The platform earned money by connecting the buyer with someone who could produce the image.
Why they are disappearing: Generative AI removes much of that transaction for routine work. A marketing team can describe an image, generate multiple versions internally, and revise them without commissioning an outside creator.
Hard evidence: A CESifo study on online freelance work estimated a 17% decline in image-creation job postings after image-generating AI arrived. A Society of Authors survey found 26% of illustrator respondents reported losing work because of generative AI, while 37% reported reduced income.
Klarna supplied an unusually concrete example from the buyer side. The fintech company said AI helped it save $1.5 million in image-production costs in Q1 2024, equivalent to $6 million annualized, while producing more than 1,000 AI-generated images during the quarter.
AI replacement: Midjourney, DALL-E, Adobe Firefly, and similar image-generation systems let businesses produce routine creative assets internally.
Counterpoint: Complex art direction, consistent characters, distinctive styles, and high-value brand work remain much harder to commoditize. AI is putting the most pressure on simple, repeatable production work.
4. Generic stock-image marketplaces
What they used to sell: Search a giant library, find an image close enough to what you need, and pay to license it.
Why they are disappearing: Generative AI flips that model around. Instead of searching through thousands of existing images for the closest match, customers can describe exactly what they want and generate it.
Hard evidence: Shutterstock reported that Q2 2026 Content revenue fell 17% to $165.7 million. Paid downloads declined from 112.6 million a year earlier to 98.7 million. The company primarily attributed the Content decline to weak new-customer acquisition rather than assigning a specific percentage to AI.
But individual buyers are already documenting direct substitution. Klarna said its use of generative AI had removed its need for stock imagery.
AI replacement: Generative image models can produce custom commercial imagery from a prompt rather than requiring users to license a pre-existing asset.
Counterpoint: Documentary photography, news imagery, celebrity and event photos, rights assurance, and other difficult-to-reproduce content retain value. Shutterstock’s total 2025 revenue also increased, partly reflecting acquisitions. AI is squeezing generic stock imagery more clearly than the entire visual-licensing business.
5. Generic AI copywriting startups
What they used to sell: A dedicated subscription for generating product descriptions, blog posts, emails, social copy, and advertising variants using prompts and templates.
Why they are disappearing: Text generation has become a baseline capability. ChatGPT and other general assistants can produce marketing copy, while office suites increasingly bundle writing assistance into software businesses already use.
That leaves a difficult question for a standalone copywriting startup: what exactly is the customer paying extra for?
Hard evidence: Jasper, one of the best-known startups from the first generative-AI wave, cut roles in 2023 and shifted its focus toward midsize and enterprise marketing teams. CEO Dave Rogenmoser tied the move to the pace of technological change and the proliferation of consumer AI tools.
In January 2025, Google made Gemini AI features part of Workspace business plans, eliminating the need for a separate Gemini add-on and further reducing the scarcity of AI-generated writing.
Research into online freelancing provides another signal. A CESifo study estimated a 21% relative decline in automation-prone writing and coding job postings within eight months of ChatGPT’s launch, though that figure covers both categories and does not directly measure copywriting software subscriptions.
AI replacement: General-purpose AI assistants and AI bundled into productivity software.
Counterpoint: Jasper itself illustrates the escape route. Brand controls, enterprise governance, proprietary context, integrations, campaign management, and measurable marketing outcomes can still support a business. The disappearing product is generic text generation.
6. Undifferentiated translation platforms
What they used to sell: Customers submitted text and paid a platform or service provider to translate it, often per word or per project.
Why they are disappearing: Businesses can increasingly produce a first translation internally and pay humans only for editing, specialist terminology, cultural adaptation, or verification. That reduces the billable human work tied to basic language conversion.
Hard evidence: In a 2024 Society of Authors survey, 36% of translator respondents said they had lost work because of generative AI and 43% reported reduced income.
Klarna provides evidence from the other side of the transaction. The company reported cutting spending on external marketing suppliers by 25%, explicitly including translation among several supplier categories, although it did not disclose how much of the reduction came from translation alone.
AI replacement: AI translation systems such as DeepL and general-purpose language models increasingly handle routine first-pass translation.
Counterpoint: The evidence here is mixed. More than half of language-service providers in one 2024 industry review were growing, and DeepL itself has attracted major investment. Specialist translation, localization, legal accountability, and human review remain valuable. Basic language conversion is the part losing scarcity.
7. Plain transcription resellers
What they used to sell: Upload audio, receive text, pay per minute or through a monthly subscription.
Why they are disappearing: Speech recognition is becoming infrastructure. Open-source software can perform the conversion, while operating systems, recording apps, meeting platforms, and productivity software increasingly include transcription automatically.
Hard evidence: The MIT-licensed faster-whisper implementation reports performance up to four times faster than the original Whisper implementation while using less memory, giving developers another route to lower-cost self-hosted transcription.
Apple has also moved transcription directly into software customers already own. With macOS Sequoia, Notes gained audio recording, transcription, and summarization capabilities.
AI replacement: Open-source speech recognition and transcription built directly into devices and applications.
Counterpoint: Voice AI itself is booming. Deepgram raised $130 million at a $1.3 billion valuation in January 2026. Human transcription also retains value where accuracy and accountability matter. What is becoming difficult to defend is the thin middleman that does little more than convert audio into text.
8. Paid code-autocomplete-only startups
What they used to sell: AI-generated suggestions for the next few lines of code inside a developer’s editor.
Why they are disappearing: Companies with much larger developer ecosystems increasingly subsidize basic autocomplete. At the same time, the frontier has shifted from suggesting code to agents that can work across repositories and complete multi-step development tasks.
Hard evidence: GitHub launched Copilot Free in December 2024 with 2,000 code completions and 50 chat messages per month.
Google went much further in February 2025, offering individuals Gemini Code Assist with up to 180,000 code completions per month for free.
AI replacement: Free or bundled coding assistance from major developer platforms.
Counterpoint: AI coding startups are emphatically not disappearing. Cursor reported more than $500 million in annual recurring revenue in June 2025 and crossed $1 billion in annualized revenue later that year. The pressure is on startups selling autocomplete as the product. Companies selling an entire AI development environment are proving that developers will still pay handsomely for something better.
9. Single-purpose photo-cleanup apps
What they used to sell: Download an app to remove an unwanted object, clean up a photo, fix blur, or perform another narrow editing task.
Why they are disappearing: Those features are moving into the default photo library. Once the phone or computer can do the edit directly, users have less reason to find, install, and pay for another app.
Hard evidence: Google expanded free access to Magic Eraser, Photo Unblur, and other editing tools in 2024. Apple later added Clean Up to Photos on supported devices, letting users remove distracting elements without a separate editing app.
By late 2025, Google was pushing the model further with conversational photo editing, allowing users to describe edits using text or voice.
AI replacement: Google Photos and Apple Photos increasingly absorb the basic editing functions once handled by specialist apps.
Counterpoint: Commercial photography workflows are a different market. Photoroom, for example, has expanded into broader visual-ad and commerce workflows. Again, the disappearing opportunity is the single-purpose feature, not sophisticated image software.
10. Basic “chat with a PDF” and document-summary startups
What they used to sell: Upload a PDF, ask questions about it, generate a summary, or extract a particular answer.
Why they are disappearing: Document Q&A is becoming part of the document itself. If Acrobat, Google, or a general AI assistant already understands the file, moving it into a separate service simply to ask questions becomes harder to justify.
Hard evidence: Adobe priced Acrobat AI Assistant at $4.99 per month for individual Reader and Acrobat users in 2025, bringing AI explanations, summaries, and document comparison into one of the most widely used PDF ecosystems.
Google’s source-grounded notebook product similarly lets users load documents and interact with their contents, with substantial functionality available before an upgrade is required.
AI replacement: Acrobat AI Assistant, Google’s notebook AI tools, and general-purpose assistants with native document analysis.
Counterpoint: The evidence here shows feature absorption rather than documented startup contraction. Specialist legal, financial, scientific, or enterprise document systems can still create value through accuracy, permissions, workflow integration, and domain expertise. “Upload PDF and chat” alone is becoming the commodity.
The startup isn’t disappearing. The feature is.
The evidence points to something more interesting than an AI extinction event.
Some AI startups are growing at extraordinary rates. Cursor crossed $1 billion in annualized revenue. AI customer-service startup Sierra reported reaching $100 million in ARR. Lovable reported $200 million ARR. ElevenLabs said it surpassed $500 million ARR.
What separates many winners from businesses under pressure is not whether they use AI. It is how much value remains after the underlying AI capability becomes cheap and widely available.
AI is raising the minimum amount of differentiation required to build a standalone software company.
A feature can be copied. A model can become cheaper. A capability that costs $20 a month today can appear inside software customers already pay for tomorrow.
The harder things to commoditize are the layers above it: proprietary data, distribution, workflow integration, trust, networks, domain expertise, and measurable business outcomes.
That may be the defining startup lesson of the AI era.
2019: That’s a startup.
2023: That’s an AI startup.
2026: That’s a button.
The opportunity now is figuring out what comes after the button.
Final Evidence Ranking
The evidence is not equally strong across all 10 categories. A 3/5 score does not mean startups in that category are shutting down. In several cases, the evidence instead shows that the core capability is being absorbed into larger platforms, weakening the economics of selling it as a standalone product.
| Rank | Startup type | Evidence | What the evidence establishes | Main limitation |
|---|---|---|---|---|
| 1 | Paid homework-answer subscriptions | 5/5 — Very strong | Severe financial decline; explicit AI attribution | Primarily one major public-company proxy |
| 2 | Search-dependent answer-content startups | 4/5 — Strong | Lower click-through associated with AI answers | Observational; not startup revenue |
| 3 | Commodity illustration/image-production marketplaces | 4/5 — Strong | Demand declines plus buyer-reported substitution | Startup impact inferred from underlying work |
| 4 | Generic stock-image marketplaces | 4/5 — Strong | Falling usage/revenue plus direct buyer substitution | AI share of decline unquantified |
| 5 | Generic AI copywriting generators | 4/5 — Strong | Retrenchment, bundling, and adjacent demand loss | No category-wide subscription series |
| 6 | Undifferentiated translation platforms | 3/5 — Meaningful but mixed | Reported work/income losses and insourcing | Voluntary survey; many providers growing |
| 7 | Plain transcription resellers | 3/5 — Meaningful but mixed | Open-source substitution and built-in capability | Voice infrastructure is growing |
| 8 | Paid code-autocomplete-only startups | 3/5 — Meaningful but mixed | Generous free platform alternatives | Broader coding businesses growing strongly |
| 9 | Single-purpose photo-cleanup apps | 3/5 — Meaningful but mixed | Default apps absorbing core functions | No measured category contraction |
| 10 | Basic PDF-chat/document-summary tools | 3/5 — Meaningful but mixed | Cheap incumbent integration and generous baseline access | Displacement remains commercially unquantified |